Key takeaways
- Using the equity in your home doesn’t have to mean replacing your first mortgage, because a home equity line of credit sits beside it and leaves it exactly as it is.
- A home equity line of credit is a limit you can borrow against, not a lump sum, so you use what a project or expense actually needs.
- Early in 2026, more than half of all the equity homeowners took out came through a second loan, according to the data firm ICE.
- A cash-out refinance is the other main way to use equity, and it replaces your first mortgage with a new, larger one, so it helps to understand both before you choose.
- Nothing on this page is an approval, because what you can borrow depends on your credit, your income and what your home is worth, and a CPA can speak to the tax side.
If you’re happy with your first mortgage, you’ve probably wondered whether using your equity means giving it up. Good news: it doesn’t have to.
A lot of homeowners are holding a first mortgage they’re glad to have, and many of them assume that using their equity automatically puts it at risk. The data suggests more and more people have figured out otherwise.
What most people picture when they hear “use your equity”
Equity is the part of your home you’ve paid off or gained in value, which is the difference between what the home is worth and what you still owe. Most of us picture only one way to turn it into cash, and that’s a cash-out refinance. You replace your current mortgage with a brand new, larger one, and you take the difference as cash. For some homeowners that’s a great fit, and I’ll come back to it below.
The part that surprises people is what a refinance does to the loan you already have. Your first mortgage is paid off and replaced, so the terms you built over the last few years get swapped for new ones. If you’re attached to the loan you have, that can feel like an expensive trade for a little cash, and it’s the reason a lot of homeowners tell me they’ve ruled out their equity before they ever picked up the phone.
The other way: a second loan that sits beside the first
A home equity line of credit, usually called a HELOC, is a second loan secured by your home. Your first mortgage stays exactly as it is, with the same lender and the same terms, and the line of credit is added next to it. You get approved for a limit, and you borrow against that limit as you need it.
That last part matters more than it sounds. A line of credit is a limit, not a lump sum. If a project runs a little long, the room to cover it is already there. If you never use all of it, you pay interest only on what you actually borrow. Interest on lines like this can change over time, so when we talk I’ll walk you through how it’s set and what to expect.
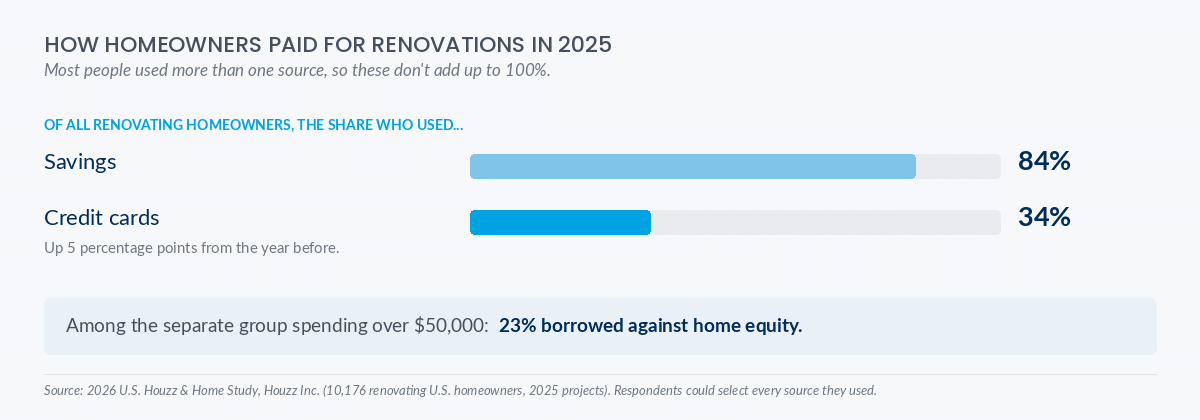
If you’re weighing a specific project, I put together a separate comparison of every common way people pay for one. You can find it in Got the project list? There’s more than one way to pay for it, which covers savings, credit cards, personal loans, a home equity line and a cash-out refinance side by side.
What the numbers say homeowners are doing
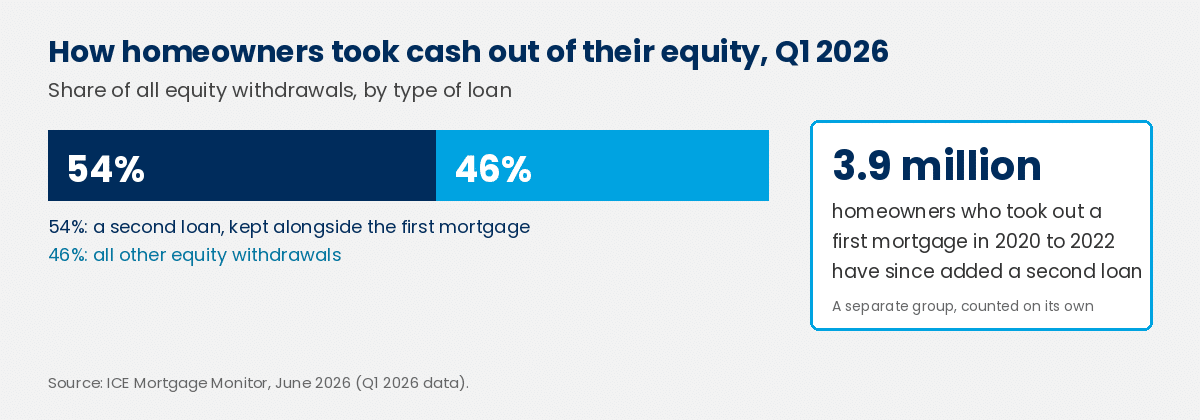
ICE, the company that tracks mortgage data across the country, reported in its June 2026 Mortgage Monitor that more than half (54%) of all the equity homeowners took out in the first quarter came through second loans. ICE said borrowers were choosing that route to preserve their existing first-mortgage rates, and that second-loan withdrawals had their strongest first quarter in nearly two decades.
The same report found that 3.9 million people who took out a first mortgage between 2020 and 2022 have since added a second loan. That’s a big group of homeowners who looked at the mortgage they had, decided it was worth keeping, and found another way to use what their home had gained in value. Cash-out refinances also reached their highest first-quarter level since 2022, so neither route is going away.
There’s one more number I find helpful for context. In its August 2026 report, ICE estimated that about 47.5 million mortgage holders have what it calls tappable equity, which works out to roughly $212,000 per borrower on average. ICE defines that as the equity a homeowner could borrow against while still keeping 20% of the home’s value as a cushion. Please treat that figure as a snapshot of the whole country and not a prediction for your house. Your own number depends on what your home is worth today, what you owe, and what a lender can approve based on your credit and income.
Two ways to use equity, side by side
Both routes can put cash to work for something that matters to you, and which one fits depends on your situation. A home equity line leaves your first mortgage alone and gives you a limit to borrow against over time, which tends to suit projects and expenses that come in pieces. A cash-out refinance replaces your first mortgage and gives you the money up front, which can make sense when you’re ready to reset the whole loan anyway.
I’d rather you understood both before choosing, because the right answer depends on things only you know, like how long you plan to stay, how you feel about the loan you have, and how much you need and when. That’s the conversation I enjoy having with homeowners.
A note about paying off other balances
Some homeowners use a home equity line to pay off other debts, like credit cards. If you’re considering that, please know what you’re trading. Those balances aren’t tied to your house today, and once they’re moved into a loan backed by your home, they become debt secured by your home. It can also stretch the time it takes to pay them off. Some homeowners decide that trade is worth it, and I want you to make that choice with your eyes open.
What the process looks like
The process is more ordinary than people expect. You start with a conversation about what you want to do and what your current mortgage looks like. Then there’s an application, a look at your income and credit, and an estimate of what your home is worth. If you move forward, there’s a closing, much like the one you did for your first mortgage. The timeline depends on the lender and on how quickly the paperwork comes together, so I won’t promise a number of days here.
I’m a mortgage loan officer, not a financial planner or a tax advisor. I can explain how a loan like this works and how it fits next to your first mortgage, but questions like how it affects your taxes or your long-term goals are ones I’d want you to take to a CPA or a licensed financial planner. I’m always glad to work alongside them.
Your self-check before we talk
This isn’t an approval or a qualification test. It’s a short list to help you walk into the conversation prepared, so you can get real answers faster. Check off what you already know, and bring whatever’s left.
- ☐ I know roughly what my home is worth today, based on recent sales near me or a recent appraisal.
- ☐ I know about how much I still owe on my first mortgage, from my latest statement.
- ☐ I know what I want to use the money for, and roughly when I’d need it.
- ☐ I’ve decided whether I’d like to keep my first mortgage exactly as it is.
- ☐ I have my last two pay stubs or other income records handy.
- ☐ I know what other balances I’m carrying, in case I want to talk about them.
- ☐ I’ve written down my questions, including how the interest works and what the costs are at closing.
- ☐ I’ve thought about whether a CPA or financial planner should weigh in.
If you’ve checked a few of these, you’re ready for a good conversation, and if you’ve checked none, that’s fine too. Whenever you’re ready, give me a call or reach out through our contact page, and we’ll sort out the rest together.
This page is general information, not a commitment to lend or an offer of credit. Loans are subject to credit approval, and what you may qualify for depends on your credit, income, home value and current mortgage.