Home Buying Tips

Can You Buy a Home With Student Loan Debt? Here’s What Actually Matters to Lenders

Can You Buy a Home With Student Loan Debt? Here’s What Actually Matters to Lenders 5774 3849 Your Loan Officer for Life

Key Takeaways

  • How your student loan payment actually factors into DTI (it’s not always your full payment) 
  • Which loan programs — FHA, Conventional, VA, USDA — treat student debt most favorably 
  • How to calculate your own DTI before you talk to a loan officer 
  • Down payment assistance and co-borrower options if your budget is tight 


If you’re carrying student loan debt and wondering whether homeownership is realistic, here’s the direct answer: it is. Student loan debt is one input in a mortgage application, not a disqualifier. Thousands of homeowners closed on a mortgage last year while still repaying student loans — the difference between the ones who qualified and the ones who didn’t usually came down to how their debt-to-income ratio was calculated and which loan program they used. 

This guide walks through exactly how underwriters treat student loan debt, which loan programs give you the most room, and the concrete moves that improve your approval odds. 

How Student Loans Affect Mortgage Approval 

Lenders aren’t evaluating your student loans in isolation. They’re looking at the full picture: your student loan payment, credit history, income stability, and available savings, weighed together. Student debt influences your application in three specific ways: 

  1. It counts toward your debt-to-income (DTI) ratio. This is the number that matters most. Underwriters compare your total monthly debt obligations to your gross monthly income to determine how much mortgage payment you can realistically absorb. 
  2. It affects how much you can save. A high monthly student loan payment competes directly with your ability to build a down payment and closing cost reserve — which is why timing matters as much as qualification.
  3. It shows up on your credit report. Payment history on student loans is scored the same way as any installment debt. Consistent, on-time payments build your credit profile; missed payments do the opposite.


The detail most articles skip: how your student loan payment is counted varies by loan program, and it’s not always your actual monthly bill. This is where working with a lender who underwrites across multiple program types actually matters. 

How Different Loan Programs Calculate Student Loan DTI 

This is the part that determines whether you qualify — and it’s where Milend’s ability to originate across FHA, Conventional, VA, and USDA loans gives you more paths to approval than a single-program lender. 

FHA Loans 

  • 3.5% down payment minimum 
  • More flexible credit score requirements than conventional financing 
  • DTI calculation: if your loan is in deferment or income-driven repayment, FHA guidelines generally use a percentage of your outstanding balance rather than your actual reported payment — which can work for or against you depending on your balance and current payment amount. Your loan officer runs both scenarios. 


Conventional Loans 

  • 3–5% down payment for qualifying first-time buyers 
  • Best pricing typically available to borrowers with stronger credit 
  • DTI calculation: your actual documented payment is used when available; if your loan is deferred or in IDR with no verified payment, a calculated percentage of the balance applies instead 
  • See how Conventional stacks up against FHA in more detail: Conventional and FHA Loans: Which Is Best? 


VA Loans 

  • Available to eligible veterans, active-duty service members, and qualifying surviving spouses 
  • 0% down payment, no monthly private mortgage insurance 
  • Generally the most flexible DTI treatment of any program for student loan borrowers 


USDA Loans 

  • 0% down payment 
  • Available for eligible rural and suburban properties within USDA-designated areas 
  • Income limits apply, so this program fits a specific income and location profile — worth checking property eligibility before assuming it’s off the table 


Because the right answer depends on your specific balance, repayment plan, and location, this is a conversation better had with a loan officer than settled by a blog post. Browse our full range of purchase loan options or talk to a Milend loan consultant about which program fits your student loan situation. 

Calculate Your Own DTI Before You Apply 

Knowing your number before your first conversation with a lender puts you in control of the conversation. Here’s the formula: 

Add up your total monthly debt payments (student loans, auto loans, credit cards, any other installment or revolving debt) 

Divide that total by your gross monthly income (before taxes) 

Multiply by 100 to get your DTI percentage 

What counts as a good DTI: Under 36% is considered strong by most underwriting standards. Many programs allow up to 43%, and some — particularly FHA and VA — extend further with compensating factors like strong credit or significant reserves. 

Ways to lower it before applying: 

  • Pay down revolving balances (credit cards) rather than installment debt — it moves the needle faster 
  • Ask about switching to an income-driven repayment plan if your current payment is high relative to your balance 
  • Hold off on new credit applications, auto loans, or financed purchases in the months leading up to your mortgage application 

Your Credit Score Still Carries the Most Weight 

Student loans are one piece of your credit profile, not the whole picture. Here’s how your score actually breaks down: 

Factor Weight 
Payment history 35% 
Amounts owed 30% 
Length of credit history 15% 
New credit 10% 
Credit mix 10% 

On-time student loan payments contribute positively here — a consistent repayment history is evidence of financial reliability, not a red flag. The most common ways to strengthen your score before applying: keep credit utilization under 30%, avoid opening new credit accounts in the 6 months before applying, and dispute any credit report errors immediately rather than letting them sit. 

If your credit history is more of an obstacle than your student loans, our credit score resources cover more on how lenders read your report — there are more paths through this than most borrowers assume. 

Down Payment Assistance Options 

If a down payment feels like the harder obstacle than DTI, down payment assistance (DPA) programs are worth exploring before you assume you need to save the full amount yourself. These typically come as grants, forgivable loans, or deferred second loans, and eligibility often depends on income, location, occupation (teachers, healthcare workers, and public servants frequently qualify for dedicated programs), or first-time buyer status. 

Availability varies significantly by state — your loan officer can walk you through the specific DPA programs active where you’re buying and whether you qualify given Milend’s licensed footprint. For down payment context specifically, see: Is a 20% Down Payment on a Home Necessary? Or if this is your first purchase, start with our first-time buyer resources. 

Consider a Co-Borrower 

If your DTI or income alone doesn’t get you to your target loan amount, adding a co-borrower — a spouse, partner, or family member — combines income to potentially qualify for a larger loan or better terms. 

Before moving forward with this option, know what you’re agreeing to: 

  • Both borrowers are legally responsible for the full loan amount, not a proportional share 
  • Both names appear on the title, meaning shared ownership 
  • A missed payment affects both credit profiles, not just the primary borrower’s 

This is a significant financial commitment between both parties — worth a direct conversation before it becomes part of your application. Our mortgage FAQ covers more terms like this if you want to go deeper before your first call. 

Review Your Student Loan Terms Before You Apply 

Before you start the mortgage process, it’s worth taking a hard look at your student loans themselves. Check your current payment, interest rate, balance, and repayment plan. Depending on your situation, refinancing to a lower rate, switching to an income-driven plan, or making extra principal payments in the months before applying could meaningfully change your DTI picture. (Note: this refers to refinancing your student loans, not your mortgage — though if you’re weighing your own mortgage refinance options down the road, that’s a separate conversation worth having with your loan officer too.) 

The Bottom Line 

Student loan debt is a factor in your mortgage application — not a barrier to it. The path to approval usually comes down to three things: which loan program treats your specific repayment situation most favorably, whether you’ve calculated your real DTI before applying, and whether you’re using every available tool (DPA, co-borrowing, credit optimization) that fits your circumstances. 

Milend has been guiding homebuyers through exactly this kind of decision since 1995. As a family-owned, Atlanta-based lender, we underwrite across FHA, Conventional, VA, USDA, Jumbo, and specialty programs — which means we’re not fitting your student loan situation into one program’s rules. We’re finding the program built for it.  

What I get asked?

Does student loan debt disqualify you from getting a mortgage? 

No. Student loan debt is one factor lenders weigh alongside credit score, income, savings, and overall debt-to-income ratio. It affects the size of the loan you qualify for, not your eligibility to apply. 

Which mortgage is easiest to qualify for with student loans?

It depends on your repayment status and balance. FHA and VA loans generally offer more flexible DTI treatment for borrowers with student debt, but the right fit depends on your specific numbers — a loan officer can run scenarios across programs. 

What DTI do I need to buy a house with student loans? 

Under 36% is considered strong. Many programs accept up to 43%, and some government-backed programs allow higher ratios with compensating factors like strong credit or cash reserves. 

Can I use a co-borrower to qualify with student loan debt? 

Yes. Adding a co-borrower combines income, which can offset a high DTI. Both parties become fully responsible for the loan and share ownership, so it’s worth a direct conversation before applying together. 
6 Ways to Buy a Home With Little-to-No Money Out of Pocket

6 Ways to Buy a Home With Little-to-No Money Out of Pocket 6240 4160 Your Loan Officer for Life

Key Takeaways

  • Which loan programs allow $0 down, and who qualifies 
  • How down payment gifts and assistance programs actually work 
  • When it makes sense to ask a seller to cover closing costs 
  • The tradeoffs of a low down payment you should know before you commit 


Not having a large down payment saved up is one of the most common reasons people assume homeownership is out of reach. It usually isn’t. Between zero-down loan programs, down payment gifts, assistance funds, and seller-paid closing costs, there are several legitimate paths to closing on a home without draining your savings account first. 

Here are six ways to reduce what you need out of pocket, plus what to weigh before choosing one. 

See If You Qualify for a VA Loan 

Active-duty service members, veterans, and eligible surviving spouses can access one of the strongest homebuying benefits available: a VA loan with no minimum down payment requirement. Because the loan is backed by the Department of Veterans Affairs, lenders can extend financing without requiring a down payment or ongoing private mortgage insurance — instead, most VA loans include a one-time VA Funding Fee, and some borrowers are exempt from that as well. 

For eligible buyers, this is typically the lowest out-of-pocket path to homeownership available. 

Consider an FHA Loan 

FHA loans allow a down payment as low as 3.5%, and that 3.5% doesn’t have to come entirely from your own savings — it can be covered by a financial gift from a family member or contribution from a qualified nonprofit or government program. Sellers can also contribute up to 6% of the sale price toward closing costs. 

The tradeoff: FHA loans require mortgage insurance regardless of your down payment size, so it’s worth weighing that ongoing cost against the lower barrier to entry.

 Look Into a Homebuyer Assistance Program 

Down payment assistance (DPA) programs exist at the state, local, and nonprofit level, and many extend beyond first-time buyers to previous homeowners as well. These typically come as grants, forgivable loans, or deferred second loans — funding structures where you’re not simply taking on more debt to cover your down payment. Availability and eligibility vary significantly by location, so this is worth a direct conversation with your loan officer rather than assuming you don’t qualify. If this is your first purchase, our first-time buyer resources are a good starting point, and it’s also worth reading whether a 20% down payment is actually necessary before ruling anything out. 

Don’t Overlook the USDA Loan 

USDA loans — sometimes called rural development loans — offer a zero down payment option for eligible properties in designated rural and, in many cases, surprisingly suburban areas. Don’t assume your target area doesn’t qualify without checking; USDA eligibility maps cover more ground than most buyers expect. Mortgage insurance is required, and both loan limits and income restrictions vary by area, so property and income eligibility should be confirmed early in your search rather than after you’ve found a home.

Receive a Down Payment Gift

If a family member is able to gift you funds toward your down payment, most loan programs allow it — but the paperwork matters. Lenders require a documented paper trail showing who gifted the funds, how and when the money was transferred, and written confirmation that repayment isn’t expected. The amount you’re allowed to accept as a gift varies by loan program, so confirm the specifics with your loan officer before the funds move. For more on how gift funds interact with your overall closing costs, see Can You Reduce Your Closing Costs, and Should You? 

Have the Seller Pay Closing Costs 

Seller-paid closing costs, also called seller concessions, depend heavily on your local market conditions. In a buyer’s market, where inventory exceeds demand, sellers are often willing to negotiate on closing cost contributions to keep a deal moving. In a competitive seller’s market, that same request may not land — but it’s still worth asking, since many sellers value a fast, certain close over squeezing out every dollar. How much a seller can contribute is also capped by your loan program, so this is another detail your loan officer can confirm before you write an offer. 

What to Weigh Before Choosing a Low Down Payment Option 

Reducing your out-of-pocket cost at closing is genuinely useful, but it comes with tradeoffs worth understanding upfront: 

  • Mortgage insurance may be required depending on the loan program and down payment size, which adds to your monthly payment. 
  • Less equity at the start means less “cushion” if you need to sell within the first few years, and potentially a somewhat higher interest rate since the lender is taking on more risk. 
  • Slower equity build means it may take longer to reach the point where selling nets a meaningful profit — a bigger consideration if you expect to move again soon than if you’re planning to stay long-term. 

If putting a full 20% down would leave you without a financial cushion for emergencies, a lower down payment option is often the smarter move — not a compromise. The right call depends on your full financial picture, which is exactly what a conversation with a loan officer is for. 

The Bottom Line 

A thin savings account doesn’t have to mean a delayed home purchase. Between VA and USDA’s zero-down options, FHA’s gift-fund flexibility, down payment assistance programs, and seller concessions, most buyers have more than one realistic path to closing — the right one just depends on your eligibility, your market, and your long-term plans. 

Milend has been helping buyers navigate exactly this decision since 1995. As a family-owned, Atlanta-based lender, we underwrite across FHA, VA, USDA, and Conventional programs, so we’re matching you to the loan built for your actual financial picture — not the one that’s easiest for us to originate. 

Questions I get asked?

Can I really buy a home with no money down?

Yes, in certain situations. VA loans and USDA loans are two programs that may allow qualifying borrowers to purchase with no down payment. VA loans are available to eligible active-duty service members, veterans, and qualifying family members. USDA loans are available in designated rural and many suburban areas and carry income eligibility requirements. Whether either program fits your situation is worth a direct conversation with a Milend loan officer. 

What is the minimum down payment for a first-time homebuyer?

It depends on the loan program. FHA loans typically require as little as 3.5% down. Conventional loans may be available with as little as 3% down for qualifying borrowers. VA and USDA loans may allow zero down for those who meet eligibility requirements, and down payment assistance programs at the state or local level may reduce what you need to bring to closing further still. 

How does a VA loan work with no down payment?

The VA loan program is backed by the Department of Veterans Affairs and is one of the most valuable homebuying benefits available to eligible servicemembers, veterans, and qualifying surviving spouses. Because the VA guarantees a portion of the loan, lenders can extend financing without requiring a down payment. Instead of ongoing mortgage insurance, most VA loans include a one-time VA Funding Fee, though some borrowers are exempt.

Can a family member gift me money for a down payment?

In most cases, yes. Loan programs generally allow gift funds from immediate family members toward a down payment, but documentation requirements vary by loan type — typically including a signed gift letter confirming the amount, the source, and that repayment isn’t expected. Your Milend loan officer can walk you through the exact requirements for your loan program. 

What is a homebuyer assistance program and do I qualify?

Homebuyer assistance programs are offered through state housing finance agencies, local governments, and nonprofit organizations to help with down payments and closing costs. Eligibility and available funding vary significantly by location, and while many programs target first-time buyers within certain income limits, some are open to previous homeowners as well. 

Sale Pending sign in front of a house with grey siding.

What Does “Affordable” Really Mean When Buying a Home?

What Does “Affordable” Really Mean When Buying a Home? 4469 2979 Your Loan Officer for Life

Key Takeaways

  • Affordability is More Than a Monthly Payment
    Online estimates often leave out key costs like property taxes, insurance, HOA dues, and PMI. It’s important to look beyond the number on a home listing and calculate your real monthly budget.

  • Loan Programs Can Help You Buy with Less Out-of-Pocket
    You don’t need 20% down to buy a home. With options like FHA, VA, and down payment assistance programs, there are ways to keep upfront costs manageable—especially for first-time buyers.

  • Know Your Numbers and What You’re Comfortable With
    Lenders use guidelines like the 28/36 rule to help define affordability, but the final decision should be based on your personal budget, goals, and lifestyle after you move in. Working with a lender can help you find the right fit.

If you’ve ever been on Zillow and found a house you love, you’ve probably noticed that estimated mortgage payment box under the listing price. But here’s the thing—that number doesn’t tell the whole story.

With home prices and mortgage rates both higher than we’ve seen in years, figuring out how much house you can actually afford takes more than just looking at a monthly payment estimate online. Whether you’re buying your first home or planning a move, here’s how to evaluate affordability the right way—and how a loan expert can help you get the best terms for your situation.

Look Beyond the Monthly Mortgage Payment

When you see a monthly payment listed on a home search site, that number typically includes:

  1. Principal & Interest (based on current average rates)
  2. Maybe property taxes and insurance (though often under-estimated)
  3. Rarely any HOA fees or PMI (Private Mortgage Insurance)

What’s often missing:

  1. Actual local property taxes (which vary county by county)
  2. Current homeowners insurance premiums
  3. PMI, which applies if you’re putting less than 20% down
  4. HOA dues, which can add hundreds a month depending on the neighborhood


💡 Quick tip: Always assume the monthly estimate online is a rough guess. The actual cost may be higher or lower depending on your loan type, credit score, and local taxes.

Understand Your Real Budget

Before falling in love with a home, it helps to understand what price range you can comfortably shop in. A good rule of thumb is to stay within these ranges:

  1. 28% of your gross income = your housing budget (mortgage, taxes, insurance, HOA)
  2. 36% of your gross income = your total debts (housing + credit cards, car payments, loans)

💬 Example:

If you earn $7,000/month before taxes:

  1. Try to keep total housing costs under $1,960
  2. Keep total debts (including housing) under $2,520

Factor In Your Down Payment & Closing Costs

Most people don’t have 20% down saved, and that’s okay! There are plenty of loan programs designed to help buyers purchase with less money out of pocket:

  1. Conventional loans – often as low as 3–5% down for qualified buyers
  2. FHA loans – 3.5% down with more flexibility on credit
  3. VA loans – 0% down for eligible military service members and veterans
  4. Down payment assistance programs – available in many states for first-time buyers

🏡 The smaller your down payment, the more likely you’ll pay PMI. But with the right loan setup, it’s possible to reduce or remove PMI later.

And don’t forget closing costs, which usually run about 2–5% of the home price. Partnering with a good mortgage lender will help you navigate these options and educate you on the best loan option for you.

Know What Affects Your Interest Rate

Your interest rate isn’t just based on the market—some of the factors that go into getting your best mortgage rate include:

  1. Credit score – higher = better rate
  2. Loan amount and term – 15-year vs 30-year loans have different rates
  3. Points – you may be able to pay a little upfront to “buy down” your rate and save long-term
  4. Loan type – Conventional, FHA, VA, or even jumbo loans all price differently

Working with the right lender can make a big difference at this point because a mortgage expert can work to meet your exact financial goals and put together the best loan options around your down payment, monthly payment, and mortgage rate needs.

Calculate Your Total Monthly Payment

Here’s what your real monthly mortgage payment might include:

  1. Principal
  2. Interest
  3. Property taxes
  4. Homeowners Insurance
  5. PMI (if required)
  6. HOA fees (if applicable)

You can get a quick and easy estimate of how much home you can afford using our online Mortgage Calculator or call one of our licensed mortgage experts to run your numbers based on your actual credit, debts, income, and goals. They’ll show you a detailed breakdown, including what your upfront costs and monthly payment will really look like.

Think About Life After You Move In

Affordability isn’t just about qualifying for a loan. It’s also about feeling comfortable month to month after the move. Ask yourself:

  1. Will you have a cushion for maintenance, repairs, or upgrades?
  2. Are you still able to save for emergencies or retirement?
  3. Would you feel better with a lower monthly payment, even if it means buying a smaller home or in a different area?

The goal isn’t just to get approved—it’s to feel good about your new home and your financial life after the move.

Final Thoughts: What Can You Really Afford?

If you’re trying to figure out what you can afford in this market, don’t rely on home search estimates alone. Additional costs of homeownership like mortgage insurance, taxes, cost-of-living differences in that area, and home maintenance are rarely included in online calculators.

Homeownership is an investment in your future that makes more financial sense than renting—especially since rental prices keep rising. Once you know your real numbers and talk to a lender about loan programs that can help with your down payment, you’ll be able to house-hunt with confidence, and you may be surprised to find that your first home or next home is closer than you think.

While there are credit factors that help affordability, you don’t have to have a perfect credit score, a 20% down payment saved, or wait for lower interest rates to get approved for a home. A great lender can help you look at the full picture and find loan programs that make a home affordable for you right now.

Jerome Powell addressing the Press
2025 Mortgage Trends: Why Fed Rate Cuts Aren’t Helping Homebuyers
Read more...
Blond woman sitting in an arm chair by big open windows in a white room holding a mug up to her face.
Heating Up Your Home: Lower Your Winter Power Bill
Read more...
Jerome Powell addressing the Press

2025 Mortgage Trends: Why Fed Rate Cuts Aren’t Helping Homebuyers

2025 Mortgage Trends: Why Fed Rate Cuts Aren’t Helping Homebuyers 1280 720 Your Loan Officer for Life

Key Takeaways

  • Fed Rate Cuts Don’t Directly Lower Mortgage Rates: Despite the Federal Reserve lowering the prime rate, mortgage rates remain steady above 6.5%. Understanding the factors that influence mortgage rates can help buyers and homeowners navigate their financial decisions.
  • Housing Inventory and Economic Indicators Matter More: Key factors like housing inventory and broader economic trends often play a larger role in determining mortgage rates than changes in the Fed rate alone.
  • Planning for 2025 Housing Trends: Learn how steady mortgage rates, inventory challenges, and market trends might affect homebuying or refinancing opportunities in the coming year.

Heading into 2025, many homeowners had hoped that Federal Reserve rate cuts would lead to an adjustment in the housing market and significantly lower mortgage rates. Despite several rate adjustments late last year, interest rates on 30-year fixed-rate mortgages have held relatively steady at around 7% after an initial brief dip. The Federal Reserve’s latest rate cut of a quarter basis point in December brings total rate cuts to a 1% reduction since September 2024.

This raises an important question: Why haven’t these cuts made mortgages more affordable, and what can we expect to happen with mortgage rates in 2025?

Mortgage Rates and Fed Cuts: The Disconnect

The big disconnect between expectations and reality is that mortgage rates don’t directly follow Fed rate cuts—they respond to more complex factors like bond yields, lender margins, and market demand. While the federal funds rate sets the tone for short-term borrowing costs, reductions in the Federal Reserve’s rates don’t automatically guarantee lower interest rates on long-term assets, like your home loan.

Mortgage rates are heavily influenced by long-term economic factors, and the factor that plays into long-term mortgage rates the most is the yield on the 10-year Treasury bond. These yields are shaped by inflation, market sentiment, and global economic conditions. When inflation is high or markets are volatile, Treasury yields stay elevated and mortgage rates tend to remain high as well.

Even with the Fed trimming the Fund Rate, inflationary pressure and market uncertainty have kept mortgage rates from dropping the way potential home buyers or homeowners looking to refinance had hoped.

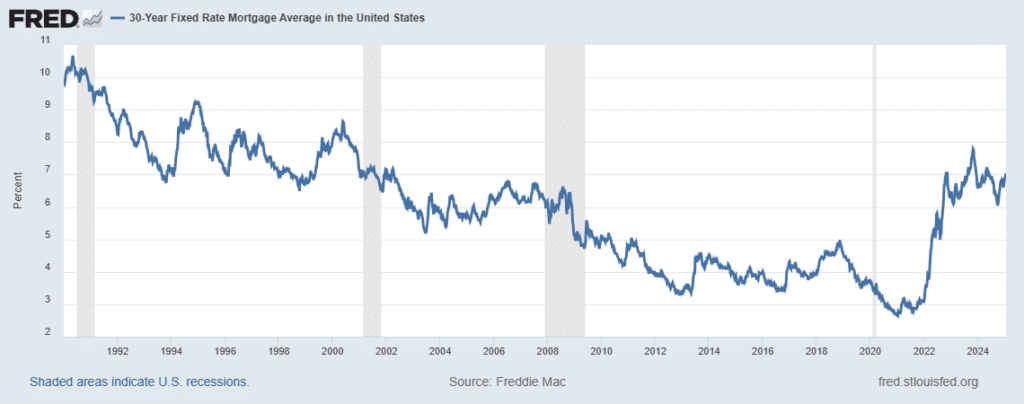
30 year Mortgage Rates Data Chart from Freddie Mac - 1990-2025


Putting Current Rates into Perspective

While mortgage rate drops haven’t matched the hype accompanying the Federal Reserve’s decision to start rate cuts last year, current rates have less to do with mortgage affordability than you might think. Those sub-3% mortgage rates many remember from 2021 were an exceptionally low anomaly – the result of aggressive intervention by the Federal Reserve during the COVID-19 pandemic, slashing the Fed Funds Rate to near zero to support and stabilize the economy.

Historically, mortgage rates in the range of 6-7% are much more representative of what we might consider “normal” market conditions. To put this into perspective, during the 1990s and early 2000s, mortgage rates routinely fluctuated between 5% and 8%. While today’s rates may seem high compared to pandemic-era lows, they are aligned with historical averages.

Current rates have a bigger effect on mortgage affordability simply because this “normal” rate environment follows on the heels of historically low mortgage rates, contributing to low housing inventory.

Inventory is Still Impacting Affordability

While mortgage rates have hogged the limelight on affordability, we can’t ignore the role limited inventory has played in keeping the housing market expensive. Many homeowners who refinanced their mortgages during the historically low 3% interest rate era are now opting to stay put, rather than sell and take on new loans at the higher rates available today. This “rate lock-in” effect has led to a stagnant housing supply, with fewer properties being listed for sale.

In an encouraging market shift, there was a notable uptick in active listings in November 2024—up 12.1% from one year prior. Over half of these homes, however, have been on the market for more than 60 days—often because they are overpriced or in less desirable condition. Despite the increase in new and existing homes being listed, the reality is that home prices do not appear to be dropping significantly any time soon.

Amid calls to build more homes to alleviate inventory shortages, market data suggests plenty of new construction listings are on the market. Rather than slashing prices to move more homes, many builders may opt to rent out homes rather than releasing more inventory. Coupled with a flood of investors paying cash and flipping properties to capitalize on pricing growth trends, these trends pressure home prices to remain high or rise further, even as demand cools due to higher rates.

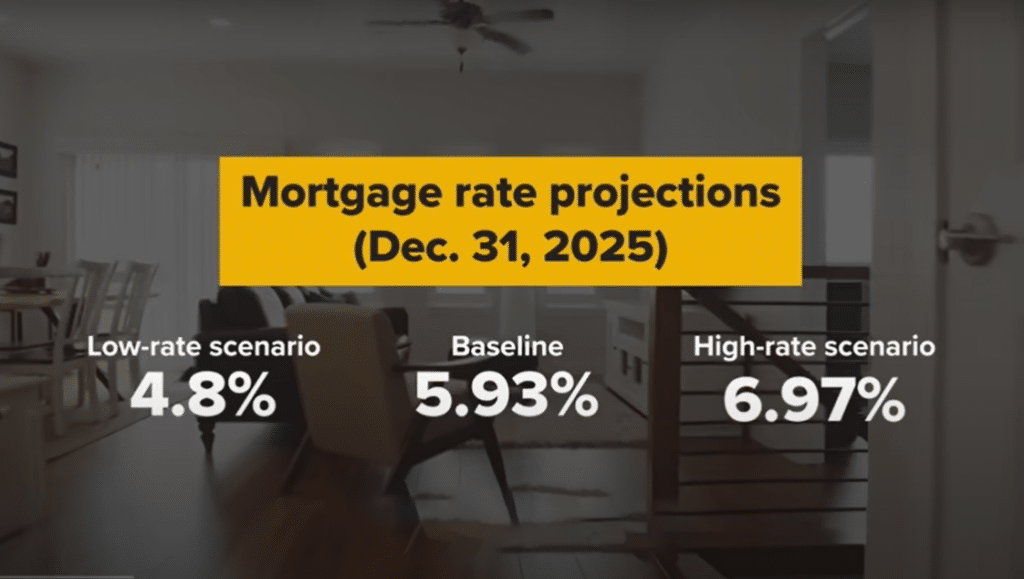
Graphic with a blurred image background. Title of the graphic, "Mortgage rate projections (Dec. 31, 2025)." Three blocks of text below the title list out the projections: "Low-rate scenario 4.8%", "Baseline 5.93%", and High-rate scenario 6.97%"

Image Source – CNBC Video “Why Fed rate cuts aren’t making mortgages cheaper”: https://www.cnbc.com/video/2024/12/21/why-fed-rate-cuts-arent-making-mortgages-cheaper

Looking Ahead to 2025

As we head into 2025, the Fed is expected to continue gradually cutting rates in an attempt to make housing more affordable, but mortgage rates may not follow suit. Expert forecasts indicate mortgage rates could remain above 5.5% throughout 2025, while others suggest rates are more likely to stabilize closer to 7-7.5% for 30-year fixed loans. As the housing market adjusts to this new reality, buyers are increasingly learning to adapt to what is now a “new normal” for mortgage rate after two years where mortgage rates averaged above 6%.

What Does This Mean for You?

If you’re planning to buy a home, it’s important to think long-term. While home prices may feel high now, home ownership remains one of the most stable and rewarding investments. Current mortgage rates are higher than they were during pandemic lows but are indicative of a normal housing market, and the “rate lock-in” effect making homeowners hesitant to sell has an expiration date.

While housing inventory is still limited, with builders and sellers holding out higher demand, we could see home prices go up from their current high. Pricing in the housing market generally increases over time and rarely adjusts down. By buying a home at current prices, you may benefit in the future as values continue to rise.

For current homeowners, exploring options to tap into your home’s equity could offer financial relief. Home Equity Lines of Credit (HELOCs) can allow you to access funds for renovations while keeping your existing mortgage rate. Leveraging a Cash Out Refinance to consolidate debt could potentially offer relief by saving you money on monthly debt payments.

Navigating the Market with Confidence

As we transition into 2025, it is clear that the housing market continues to face challenges, but it still holds opportunities for informed, proactive buyers and homeowners. That’s why it’s essential to stay updated on economic indicators like 10-year bond yields, Federal Reserve policies, and housing inventory.

Whether you’re looking to buy, sell, or leverage your equity, a knowledgeable mortgage professional can guide you through the best timing and financing options to achieve your goals.

Homeowner’s Fall Maintenance Checklist: Prepare Your Home for the Colder Months Ahead
Read more...
August Market Insights: The Big Change Coming to Real Estate for Home Sellers
Read more...
Graph paper with "Savings Tracker" written in pencil at the top and rectangles in rows and columns across the page with savings goals in them.

Smart Home Buying: Harmonize Property Dreams with Financial Wellness

Smart Home Buying: Harmonize Property Dreams with Financial Wellness 4096 2725 Your Loan Officer for Life

Key Takeaways

  • Set Realistic Budgets: Understanding your financial health is the first step in the home buying process. It’s crucial to assess your income, debts, and savings to set a realistic budget, ensuring your dream home aligns with your financial reality.
  • Plan for All Costs: Beyond the down payment and mortgage, home ownership involves additional expenses such as property taxes, insurance, maintenance, and unexpected repairs. Planning for these costs upfront can prevent financial strain down the line.
  • Think Long-Term: Your home is more than just a place to live; it’s a long-term investment. Consider future needs and lifestyle changes, ensuring the home you choose can grow with you and remain a wise investment over time.

There’s nothing quite like the journey to finding your perfect nest, is there? But, as thrilling as it is, making the dream of home ownership mesh with the reality of personal finance can feel like a balancing act.

Let me share a little story with you…Carl, eager to buy his first home, found out that saving the rest of the down payment and covering a monthly mortgage payment based on today’s home prices wouldn’t work without some careful planning and major changes to his budget. It was a learning curve, but together, we mapped out a plan that led him to his dream home without tipping the scales of his financial well-being.

The Basics of Personal Finance in Home Buying

I like to take a page out of Dave Ramsey’s book for setting a housing budget you can comfortably afford – keep it under one-third of your gross monthly salary or a quarter of your monthly take home pay. When you have a solid monthly budget in front of you, you can decide on an amount to put into monthly savings for your home dreams – pay yourself first before spending anything else. Remember, owning your home is a cornerstone of a healthy financial future.

Growing your credit score can get you better deals when it’s time to purchase or refinance a home. Some general rules of thumb include keeping credit card balances low, not opening or closing accounts, and paying your entire monthly balance. I personally use the Chase Credit Journey that comes free with my Chase Card account, but there are many options for keeping track of your score’s journey.

Preparing Your Finances for a Home Purchase

Before setting your heart on a home, let’s get your finances in tip-top shape! Start by trimming down debts and beefing up your savings—think of it as your financial fitness routine. It’s about planning ahead and making small, smart moves that lead to big wins.

One of my clients, Jake, took out some equity from his existing home to pay off high-interest credit cards with big balances six months before looking for his next home. Not only did he save a mint on monthly credit card bills to shore up his savings account, he also secured his a great rate when it came time to buy his next home!

Navigating Mortgage and Home Buying Costs

Mortgages can get complicated – that’s why it makes a world of difference to find a loan officer you trust who can walk you through each step. One of the things that I love about everyone on the Milend team is that they are the best with complicated financial pictures and knowing how to match you with the perfect loan to fit your needs. From interest rates to closing costs, they break down each step and guide you through the process.

If you prefer to do a little research on your own to get a good grasp of the process, we have a lot of good breakdowns on the mortgage process here on our blog and in our FAQs section. I want you to be as comfortable with your mortgage as you will be in your new living room.

Balancing Home Buying Goals with Long-term Financial Health

It’s easy to get swept up in the excitement of house hunting, but overextending yourself to buy a home can jeopardize your long-term financial health. I once worked with a couple who had a picture in their heads of a big house on some acreage, but they realized a charming cabin on some land fit both their lifestyle and financial goals better.

Here’s where it can be fun to really define your lifestyle goals and helpful to have a dream home checklist split into must-haves and nice-to-haves. When what really matters the most is written down in black and white, it’s easy to adjust your search to find properties that meet your needs while keeping some breathing room in your wallet.

Final Tips and Strategies for Successful Balance

Achieving harmony between your home-buying aspirations and your financial health is possible with a few key strategies:

  • Set clear, achievable goals.
  • Plan ahead and save in advance.
  • Keep an open line of communication with your loan officer!
  • Regularly review your financial plan to ensure it aligns with your home-buying journey.

Remember, every step you take towards balancing your finances and home-buying dreams is a step towards a future filled with joy, stability, and countless memories in a home that’s truly your own.

As we wrap up, I want to remind you that while the path to homeownership takes a lot of planning, it’s also an exciting adventure -one that I’d be thrilled to embark on with you. If have questions on how to balance your dream home with your financial well-being, let’s chat! Hit me up in the comments or head over our Contact page if you would rather discuss over email or the phone. Together, we’ll make your home-buying journey as joyful and fulfilling as the day you turn the key to your new home.

Navigating the Home Loan Process: Your Friendly Step-by-Step Guide
Read more...
5 Key Home Buying Trends to Watch in 2024
Read more...