Refinance

Browse MiLEND’s refinance articles for tips on lowering your rate, reducing your monthly payment, and making the most of your home equity. Our loan specialists share practical guidance to help Atlanta homeowners make smart refinancing decisions.

A living room mid-renovation with furniture under plastic dust sheets, taped moving boxes and an aluminium stepladder

Got the project list? There’s more than one way to pay for it

Got the project list? There’s more than one way to pay for it 1200 630 Your Loan Officer for Life

Key takeaways

  • Most homeowners decide how to pay for a renovation twice. Once before the first contractor arrives, and again mid-project when the budget runs over.
  • Think hard before a project takes your emergency fund with it. That’s one of the better reasons to borrow against the house instead.
  • The five ways of paying aren’t equal. You’ll pay far less interest on money borrowed against your home than on a credit card or a personal loan.
  • Refinancing isn’t the only way to reach your equity anymore, and for a lot of people it isn’t the obvious one.
  • A line of credit is a limit, not a lump sum. Size it for the project that runs over.

I was talking with someone recently who had spent three years saving for her kitchen. She had the number written down and she was proud of it, as she should have been. Then the work started, the old floor came up, and the number stopped being the number. That happens on most projects, and it’s the part almost nobody plans for.

Last week we went through which fall projects pay you back and which ones people regret. A lot of you wrote back with the same question, and it had nothing to do with garage doors. You wanted to know how to pay for it, so let’s talk that through. It’s the decision I watch people rush more than any other.
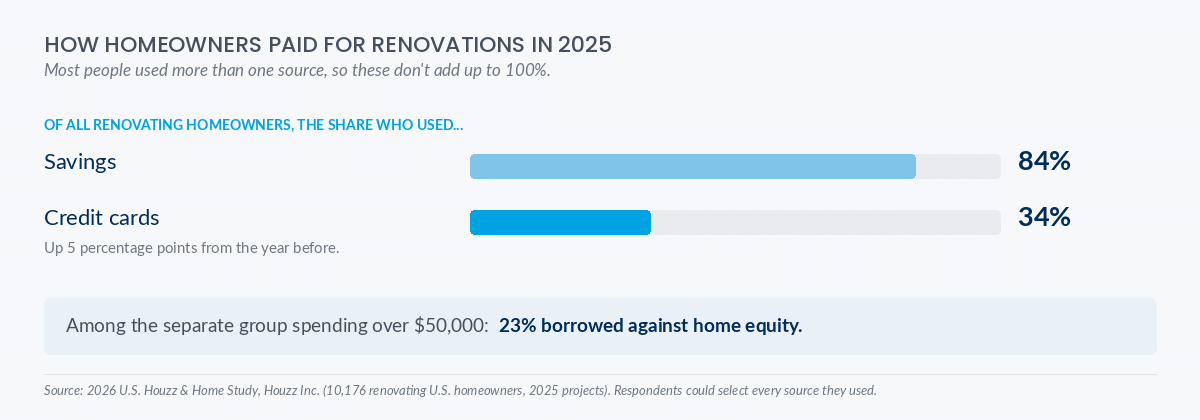
Bar chart of how homeowners paid for renovations in 2025: 84 percent used savings and 34 percent used credit cards, with a note that people could use more than one source. A separate callout says 23 percent of those spending over 50,000 dollars borrowed against home equity

The decision you make twice

Most people decide how they’ll pay for a renovation before getting a single estimate on the table. There’s a number in mind, and a plan for where it comes from. Then the tile is out of stock, or a wall comes down and something behind it needs attention, or the kitchen turns out so well that the hallway suddenly looks tired.

37% of homeowners spend past the budget they set, and most of them do it on purpose, choosing better materials or widening the scope once they can see the work taking shape. Those are usually good calls made for good reasons, but they do mean the money question gets asked twice.

The first decision happens at the kitchen table, with time to think it over. The second happens in week three, with a contractor standing in a half-finished room waiting on an answer. That second decision almost always costs more, not because the project changed, but because there was no time to think it through. That’s why I’d rather you had all of this before anyone quotes you, instead of after.

What people actually use

Most renovations get paid for out of savings, and there’s nothing wrong with that. It’s where I’d start too. What’s changed is how people cover the rest.

Credit cards now pay for part of the work on more than a third of projects, and that share climbs every year. Hardly anyone plans it that way. It happens partway through, when the money runs short and someone needs an answer the same day, and a credit card is the quickest thing in the wallet.

Most renovations get funded from more than one place, which is why the numbers in that chart add up past a hundred. Savings covers the bulk of it and something else covers the rest, and that something else is the part I’d want you choosing on purpose rather than by default.

The five ways people pay for it

These five ways of paying aren’t equal, and I’d rather say so plainly than pretend otherwise. Your own savings cost you no interest at all. Borrowing against your home costs some. A credit card or a personal loan costs the most, by a wide margin.

Savings. No lender, no paperwork, no lien on the house, and no interest to pay. Hard to beat when the money is sitting there.

The one thing I’d think about first is your emergency fund. That money already has a job. It covers a job loss, a failed water heater, a transmission. Spending it on a kitchen doesn’t make the next emergency any less likely, it just means you’ll be meeting that emergency with an empty account.

So if paying cash would clean you out, that’s a good reason to borrow against the house instead. You keep the cushion and the project still gets done.

A high-interest credit card. Fast, flexible, backed by nothing, and the most expensive way to pay for any of this. The speed is the whole appeal, and it’s also the trap.

The interest on a credit card buys you nothing. It doesn’t go into the house, it doesn’t come back at resale, and it isn’t building anything for your family. It leaves the account every month, and at credit card rates it leaves fast, which is why a credit card that started as a stopgap so often turns into the main thing you’re paying off.

There’s one narrow case where it works: something small you’ll clear in a couple of months, or a promotional rate you’ll pay off before it expires. Outside of that, a credit card becomes a bridge people end up living on, and I’ve had that conversation more times than I’d like.

A personal loan or contractor financing. Unsecured, so your house isn’t attached to it, and it’s usually quick. Nothing is backing it up though, so the interest runs much higher than a loan against your home, and you feel that difference every month for years.

Contractor-arranged financing is the one I’d read slowly, because the paperwork comes from the same people who want you to say yes to the bid. Ask who the lender actually is, and ask for the total cost over the full life of it in writing.

A home equity line or loan. On a bigger project, this is usually what we end up talking about. It’s a second loan that sits behind your existing mortgage and leaves that mortgage exactly as it is.

A line is at its best when the work happens in stages. You get a limit, you draw what you need as the job moves, and you only pay interest on what you’ve actually drawn. A loan is at its best when you already know the number: one defined job, one lump sum, one schedule.

What makes a home equity line or loan cheaper is straightforward. Your home is backing it, so the interest rate runs far below a credit card or a personal loan. On a renovation that takes a year or two to pay off, that difference adds up to real money.

A cash-out refinance. Sometimes the cheapest option depending on your scenario. You replace your existing mortgage with a larger one and take the difference, so everything stays on a single payment and a single schedule. It’s also the route that generally allows the largest loan-to-value.

The part that surprises people

For years there was one answer to “how do I get at the equity in my house,” and that answer was refinance. It’s still a good answer for plenty of families. It just isn’t the only one now, or even the usual one.

A lot of homeowners are sitting on a first mortgage they’d rather not touch. Companies who track this across most of the country, call it the lock-in effect. Earlier this year more than half of the equity homeowners took out came through second loans instead of refinancing, the strongest showing for second loans in almost twenty years. If you bought or refinanced between 2020 and 2022, there’s a fair chance I’m describing you.

Neither route wins by default. A refinance can be the cleaner move, especially if you’re not attached to your current mortgage or you’d rather keep everything in one place. What’s different now is that a second loan sits right beside it as a real choice, where a few years ago I’d have pointed almost everyone straight at refinancing. That’s what people get wrong on their own, and it’s what we can usually settle in one conversation.

Size the line for the project you’ll actually have

A home equity line of credit is a limit, not a lump sum. That makes choosing the size of the limit a separate decision from choosing how much to spend, and it’s the one I see homeowners size too small.

Set the limit against the project that runs over, not the one on the estimate. If there’s room in the line, week three costs you a phone call. If there isn’t, you’re applying for something in the middle of a build, and that’s where the expensive choices get made.

Ask me what affects the size of a line, and what fees come with keeping one open. Those vary, and they’re the part to understand before you settle on a number.

Using equity is simpler than people expect

A lot of homeowners put off calling a lender about their equity because they picture buying a house all over again, months of it, boxes of paper. Borrowing against a home you already own really isn’t that.

You already own the home. You already have the mortgage. The questions are about a property you know and a loan you’ve been paying on, and much of what I’ll ask for is paperwork already sitting in a drawer. That equity has been building the whole time your family has lived there, and putting a little of it back into the house is one of the most ordinary things a homeowner does with it.

Before you sign: a short checklist

Run through these questions before you sign a contractor’s contract, not after. Take them to whoever you’re talking to about money.

  • ☐  Write down your number, then add 20%. Plan for the version of this project that runs over, because that’s usually the one you get.
  • ☐  Decide now where the extra would come from. Make that second decision with time to think, instead of in week three.
  • ☐  Check what’s left in savings when the work is done. If the answer is “not much,” that’s an argument for using equity rather than emptying the account.
  • ☐  Ask whether this is one job or several. Staged work and a single defined job suit different options.
  • ☐  If a contractor offers financing, find out who the lender actually is. Get the total cost over the full life of it in writing first.
  • ☐  Ask whether your current mortgage is one you’d want to keep. For a lot of people it is, and that rules some options in and others out.
  • ☐  Ask what’s backing each option. Nothing backs a credit card or a personal loan, so they charge the most interest. Your home backs a refinance or a second loan, so they charge a lot less.
  • ☐  Ask what happens if the project stalls. There are answers for a delayed crew, a job that changes halfway through, and money released in stages. Get those answers before you need them.

Questions I get asked

Should I just put it on a credit card and pay it off fast? If fast really means a couple of months and you know the money’s there to do it, that can work. The trouble is that nearly everyone intends exactly that, and the balance tends to outlive the project by years. At credit card rates, that’s the most expensive version of this project there is.

Is it smarter to wait until I’ve saved the whole amount? It depends what the work is doing. A cosmetic refresh can wait, but anything holding back damage can’t, and waiting on that one usually costs more than using equity would have.

There’s also a cost to waiting that never shows up on paper. While you save, the project competes with everything else your savings is there for, prices don’t stand still, and if something gives out in the meantime it tends to land on a high-interest credit card anyway.

Can I use more than one of these? Yes, and most people do. Savings for the bulk of it, something else for the rest. The trouble starts when a high-interest credit card becomes the main source without anyone actually deciding it should.

Does it need to add value to be worth doing? No. Resale value is one way to judge a project, not the only one. Some of the best projects I’ve helped with were about living in the house rather than selling it. Just be clear with yourself about which one you’re doing.

Where to start

If you’re weighing something this fall, start with a conversation about which of these five fits your situation. It’s usually a short call, and it’s a good deal easier than most people expect. That’s the whole reason I put this together.
Increase Your Chances of a Mortgage Approval

Increase Your Chances of a Mortgage Approval 1200 628 Jason Breeland

Increase Your Chances of a Mortgage Approval

Getting approved for a mortgage is easier than you think, but you do have to be proactive, plan ahead, and set your expectations appropriately before you begin.

In many areas of the country, homes are selling quickly, and there may be fewer properties on the market. So you’ll need to be on your A-game before you start to look.

If you’re planning to purchase a home and wondering how to go about it, a good place to start is with a mortgage professional at MiLEND, Inc.  Here’s the way it will go: To gain a baseline of information, your mortgage consultant will ask about the basics, such as your income and your credit status.  He or she will run your credit information through what is called an automated underwriting system (AUS). Based on the information you provide, the AUS will show whether you can qualify for a mortgage at that time.

If for some reason you are unable to qualify, the AUS will provide very detailed information on what you need to do to qualify.  Even if you do qualify and are in a position to buy a home at that time, you still will want to find out from your mortgage consultant what payments you can afford before you start looking. You don’t want to fall in love with a home only to find out later that it’s out of your reach.  Your mortgage professional can also discuss assets and credit; lender guidelines change frequently, and you will want to know what the current guidelines mean to you.

Credit is extremely important in determining whether a lender will approve you for a mortgage. If you need to pay down or pay off debt, it may take some time. Knowing ahead means you can start now.  Don’t be disappointed later; talk to your mortgage specialist now.

This content provided by MiLEND, Inc. 

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

Low Rates Won’t Last Forever – Prepare Ahead

Low Rates Won’t Last Forever – Prepare Ahead 1024 536 Jason Breeland

Low Rates Won’t Last Forever – Prepare Ahead

Because interest rates have been so low for so long, you can’t blame people for believing this is the norm.

But families who financed homes in the 1980’s know otherwise. In fact, if it were 1980, you would be looking at mortgage rates that were in the 13–15 percent range, as opposed to today’s rates of 3–5 percent.  Rates can and do swing widely.  While it’s unlikely that rates will increase to this level anytime in the near future, if you’re purchasing a property in 2017 (especially if you are a first-time buyer), you may want to discuss your home financing options with a mortgage professional at MiLEND.

Renters in particular should be concerned about predictions that rent increases nationally are expected to outpace increases in housing prices in 2017; as a renter, at least get a picture from a mortgage professional of the alternatives available to you in the current low-rate environment.  The state of interest rates is really only one factor of many you need to consider if you are buying a home in the near future.

You also need to be aware of other factors that come into play, including your assets and your credit.  Down payments, closing costs, and other expenses incurred in the process require assets; if you need to start saving now, you’ll need to know how much.  And if your credit rating needs attention – such as paying down debt to get your debt-to-income ratios in line, or addressing items on your credit report – start now and you’ll be ahead of the game when you’re ready to launch your home search.

Even if you are planning on purchasing a home within a longer time frame (three to six months), you’ll want to discuss with a mortgage professional what may lie ahead, how to manage your expectations, and what actions to take now.

Content provided by MiLEND, Inc. 

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

An Escrow Account Can Work in Your Favor

An Escrow Account Can Work in Your Favor 1024 536 Jason Breeland

An Escrow Account Can Work in Your Favor

When you decide on your mortgage and lender, you may want to consider an escrow account.

An escrow accounts primary function is to hold money to pay for mortgage-related bills.  Escrow accounts can be a useful tool in the home purchase or refinance process.  The types of loans where escrow accounts are necessary include FHA and VA loans.  All conventional loans over an 80% Loan-to-value require escrow as well.

Escrow accounts are usually held by the lender and are set up when you take out a mortgage. To fund the account, you make an initial deposit at your loan closing. At that point, the lender calculates an amount to be added to your monthly mortgage payment for the homeowner’s insurance premiums and property taxes.  For example, if you purchase a home with property insurance totaling $100 a month, prior to closing you must pay the insurer $1,200 for the first year’s coverage.  This $100 per month will then be added to the mortgage payment and held in the escrow account until it’s needed to pay the next year’s insurance premium.

In the same way, the property tax amount will be added to the mortgage payments and held in escrow to pay the property tax bill.  These bills will be paid on the customer’s behalf from the escrow account, thanks to mortgage servicing (the handling of the daily functions of a mortgage.)  The responsibility for mortgage servicing can rest with a lender like MiLEND, Inc that follows defined procedures and are regulated by the federal government.

The service provider will make adjustments to the escrow account annually, as property taxes and insurance premiums do change. If one expense is underestimated, one would need to top up their monthly mortgage payment which can be done by writing a check for the difference.  On the other hand, overages would be refunded.  Under certain circumstances you may be able to waive the escrow account, but your lender may require a higher down payment and/or credit score.

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

Can an Appraisal Impact My Home Purchase?

Can an Appraisal Impact My Home Purchase? 1024 536 Jason Breeland

Can an Appraisal Impact My Home Purchase?

An appraisal is a valuation that your lender orders before giving you a mortgage to purchase a property.

It provides an independent assessment of what the property is really worth.  In the event you are unable to make your mortgage payments, and your lender has to sell the property, the appraisal represents the true value of the home and will inform them of the sales price.  The lending company also requires someone to physically see the property and establish if there are structural problems or flooding risks that may impact its current or future value.

You pay for the appraisal

In the case of a purchase transaction, the appraisal is ordered and completed after you and the seller have signed a sales contract.  The buyer will pay for the appraisal in advance.  Regardless of the outcome of the appraisal, this fee is nonrefundable. The lender will hire a third-party appraisal management firm to ensure the appraisal is independent, with little likelihood of bias in the report.  The property is inspected (with somewhat different criteria than a home inspection). The findings are then compared with similar properties in the same area.  After adjustments are made for differences such as the number of bedrooms and bathrooms and lot size, the appraiser comes up with a value.

Your real estate agent is also able to estimate the value of your property. He or she will have access to the same information that appraisers do, and an agent with experience should be able to come very close to the value submitted by the appraiser.  The lender, however, relies on the appraisal report, and that affects you: if the property is priced higher than its appraisal value, your lender is very unlikely to loan you the money to purchase it.

Of course, that also protects you, as you likely won’t want to pay more than the property is worth.

Content provided by MiLEND, Inc. 

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

How to Avoid Rate Lock Anxiety

How to Avoid Rate Lock Anxiety 1024 536 Jason Breeland

Ensure Your Happiness with Your Locked-In Rate

Just like the stock market, mortgage rates fluctuate. They may move daily, or even hourly, and often significantly in response to global events.

When you are negotiating a mortgage, you can “lock in” the mortgage interest rate through an arrangement with your lender. The arrangement will specify a time period over which you can lock in at the current interest rate. Before you lock in your rate, you need to ensure the rate is one you are happy with not just for now, but for as long as you have the mortgage.

Because rates fluctuate, it can—and does—happen that after you’ve locked in, rates fall. A lock is a commitment on your part and your lender’s part to accept a certain interest rate, and it’s unlikely that you will be able to get it lowered once you’ve made this commitment through the agreement with your lender. On the flip side if the rates go up you lender cannot raise you rate during the lock-in period.

To be able to lock your loan, you must be either fully approved or close to being fully approved.  This is to protect the lender, because by locking in your rate, he or she is making a commitment to the investor who will ultimately purchase your mortgage.  If the lender can’t deliver on your promised mortgage, he or she will be required to pay a fee for the use of the money between the date the rate was locked and the date the investor is notified that the loan won’t be delivered. This can become expensive for the lender. Both you and your lender should respect the mortgage lock.

Lenders are unlikely to be able to predict rates in the future, and ethically they can’t—and shouldn’t—advise you on what will happen to rates. Everyone has access to the same market information; your lender has no more insight into rates than you do. Expect your lender to explain the process, but not to help you decide when to lock in.

Content provided by MiLEND, Inc. 

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

How and When to Reduce your Closing Costs

How and When to Reduce your Closing Costs 1024 536 Jason Breeland

You Can Reduce Your Closing Costs, But Should You?

All of the costs incurred in the course of purchasing or refinancing a home are called “closing costs.” They include fees that you pay the lender, most importantly the origination fees, but other fees as well, such as appraisal, title, and recording fees.

Closing costs are usually paid from the borrower’s funds, but often you can lower them with seller credits. As well, your lender may agree to waive some of your closing costs. Sellers are often willing to cover some of your closing costs in exchange for a slightly higher purchase price, and lenders may be willing to collect less closing costs at the closing by charging a slightly higher interest rate.

Seller credits and trade-offs                                                                            

These may sound great, but note that a higher home price or a higher interest rate will cost you more in the long run. When you begin the prequalification process, consider these “benefits” but ensure you know the downsides.

Your real estate agent can help you decide the true worth of a sellers’ credit, while your lender can explain all the mortgage options available to you, including trading a higher rate for reduced closing costs. The decision, however, is yours.

Your down payment is also required at closing, and the amount of these funds (Down payment is not considered a cost) absolutely can’t be reduced by seller or lender trade-offs. Fortunately, you can use monetary gifts from close relatives to partially or completely reduce the down payment amount that comes out of your own funds, and you may also able to use approved government or other nonprofit down payment assistance programs. 

The qualified professionals at MiLEND are more than happy to offer free advice on how to avoid unnecessary costs. For over two decades, MiLEND has helped thousands of home buyers make their American dream come true. Their helpful, licensed loan experts will take the personal approach to getting you approved for a home loan, refinance, reverse mortgage, or any one of their other helpful loan products or services.  Contact MiLEND today

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

Bank Statements: The Lender’s Window to Your Wallet

Bank Statements: The Lender’s Window to Your Wallet 1024 536 Jason Breeland

Bank Statements: The Lender’s Window to Your Wallet

Your bank statements, like your credit report, are a window to your finances and your life. They are so much more than showing a lender your assets.

Lenders are looking for things like checks that have been returned for insufficient funds. If they discover these, they will want to get to the bottom of what happened. Was it caused by a bad check written to you? Was it mismanagement of your own finances? How did this happen? How often does this happen? What will keep it from happening in the future, if they loan you money for your new home?

Other red flags lenders watch for include large, non-payroll deposits that seem to have no source. Was it the proceeds from the dining room set at the garage sale last month? Was it a reimbursement check for the office supplies you recently purchased? You may be asked to write a letter of explanation for items like these during the mortgage process.

If the deposit is a gift from someone for your home purchase, and that person is an eligible donor, the lender may ask for a signed gift letter. This must state that the deposit is for the purchase of the home and that there is no expectation of repayment on your part. The lender may also ask for proof from the donor of his or her ability to give you this money. The donor must verify that it came from a legitimate source, such as a bank account, where it has been for several months.

Why does the lender need such detail? It’s because there is a good chance that your loan will be sold to investors, perhaps multiple times. Investors will take a peek through the lender’s financial window, and your lender wants them to like what they see.

Contact MiLEND today and see what all their loyal, satisfied customers have been saying all along. When you combine their level of world class customer service with the benefit of saving money, it becomes clear that MiLEND is the premier lender to use for all your loan and mortgage needs!

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

Prequalification and Preapproval Are 2 Different Documents

Prequalification and Preapproval Are 2 Different Documents 977 404 Jason Breeland

Prequalification and Preapproval Are 2 Different Documents

To the average consumer, there’s little or no difference between “prequalification” and “preapproval” letters, but to lenders – and real estate agents – there’s a world of difference.

A prequalification letter is easier for a buyer to obtain. When a prospective buyer meets a lender to find out how     much house he or she can afford, the buyer may provide certain information such as employment, income and assets without providing documented proof. The lender assumes the information provided is correct and complete, and will base their decision on the information provided. Pre-qualified borrowers are not underwritten by the lender’s underwriter.

The preapproval letter is a much more detailed process in which the lender verifies, with documented proof, the information provided by the buyer such as employment, income and assets. Tax returns will be pulled from the IRS, and the buyer’s assets will be verified.  The lender’s underwriter will review all this information to determine the amount of loan the buyer qualifies for.  The preapproved buyer will have their file completely processed and underwritten by the lender.

The next step in the process is for the lender to issue a “commitment letter.” This can only happen once the buyer has found a property, and the lender has seen the appraisal, the title, and the flood cert, among other documents. The underwriter must issue a clear-to-close approval where all conditions have been met.  This letter proves the lender is sufficiently confident with all the documentation to approve the mortgage.

It makes sense as a buyer to obtain a preapproval letter to provide to the sellers when the sellers are reviewing multiple offers.   The seller will give those offers with a preapproval letter more consideration when making a decision.

Contact MiLEND today and see what all their loyal, satisfied customers have been saying all along. When you combine their level of world class customer service with the benefit of saving money, it becomes clear that MiLEND is the premier lender to use for all your loan and mortgage needs!

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...

Conventional and FHA Loans: Which is Best?

Conventional and FHA Loans: Which is Best? 1024 536 Jason Breeland

Conventional and FHA Loans: Which is Best?

While the list of options seems to be shrinking for mortgage customers, understanding the differences between two of the major programs, Conventional or FHA, and when you might want to use each, should help to make you a more informed consumer.  Each has its own unique benefits.

Benefits to Conventional Loans

One benefit to having a Conventional loan is that there is no upfront mortgage insurance premium required and no mortgage insurance required if the loan-to-value is 80% or less of the value of the home.  FHA, alternatively, charges 1.75% of the loan amount as an upfront mortgage insurance premium and there is also a monthly mortgage insurance premium regardless of the loan-to-value position.  If the loan amount on the Conventional loan exceeds 80% of the home’s value, there will be a monthly mortgage insurance payment. In lieu of a monthly payment on conventional loans, though, a client may opt for a single premium option. Ask one of our licensed loan officers for additional information, and which is right for you. Keep in mind, again, that no upfront mortgage insurance premium is charged on conventional loans.  The monthly mortgage insurance payments may be cancelled, on conventional loans, when the loan-to-value of the mortgage reaches 78% of the home value (additional specifications may be required, per mortgage related guidelines).

Conventional loans can be on multiple property types as well. Eligible properties include: Owner-occupied properties, second homes and investor properties. FHA loans are available only for Owner-occupied properties (unless when performing a streamlined refinance, or under special circumstances).

Benefits to FHA Loans

FHA loans do not require as much of a down payment as a Conventional loan.  FHA allows a down payment of as little as 3.5% of the sales price compared to a Conventional loan that will generally require a minimum down payment of 5.0%. FHA also has lenient guidelines, pertaining to less than ideal credit history and income requirements, as opposed to Conventional loans, which can be more difficult to qualify for, in certain situations.

FHA allows for a streamline refinance on an existing FHA loan with limited credit requirements, no appraisal required, nor income verification.  Conventional refinancing requires a full credit review, income verification and the need for a new appraisal (unless when taking advantage of Fannie Mae or Freddie Mac’s Home Affordable Refinance Program).


Contact MiLEND today and see what all their loyal, satisfied customers have been saying all along. When you combine their level of world class customer service with the benefit of saving money, it becomes clear that MiLEND is the premier lender to use for all your loan and mortgage needs!

Your Ultimate Winter Home Preparation Guide
Read more...
A Financial Blueprint for a Successful Mortgage Application
Read more...