Key takeaways
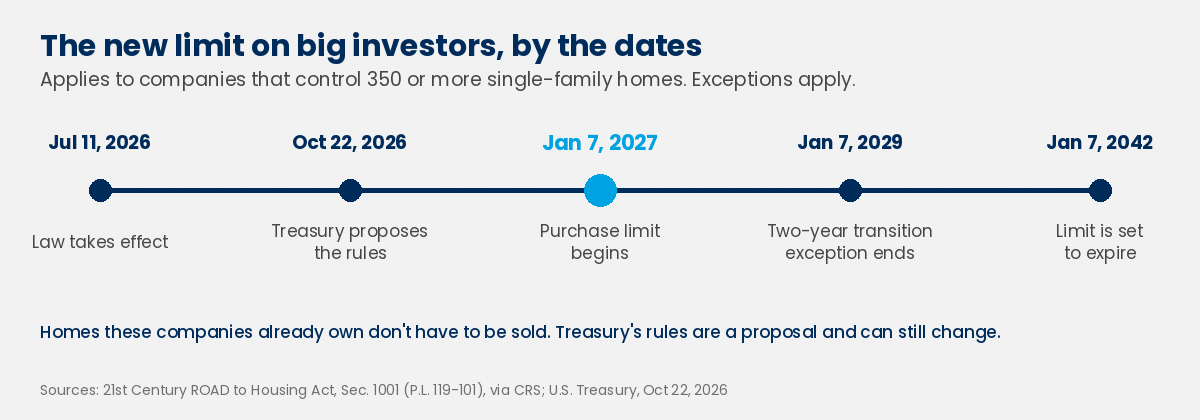
- A federal housing law that took effect in July 2026 stops companies that control 350 or more single-family homes from buying more, starting January 7, 2027.
- Homes these large investors already own don’t have to be sold, and the law includes several exceptions, such as homes built to rent and homes bought to fix up and sell.
- The Treasury Department proposed the detailed rules on October 22, 2026, and those rules can still change before they’re final.
- Nobody knows yet whether the limit will make homes easier or cheaper to buy, and the people watching the market most closely don’t agree.
- If you own a rental or two, the law isn’t aimed at you, since it only reaches companies at the 350-home level.
Over the last few months, I’ve heard some version of the same question from a lot of homeowners: is it true that big investment companies won’t be allowed to buy houses anymore? The short answer is mostly yes, starting in January. The longer answer has some exceptions and a few open questions, and those are the parts that matter if you’re thinking about buying, selling or holding onto a rental in the next couple of years.
I wanted to lay out what the law actually says, what the Treasury Department proposed in October, and what nobody knows yet. I’ve kept it to what the law and the official documents say, and I’ve noted where people disagree about what comes next.
What the new law says
The limit comes from Section 1001 of the 21st Century ROAD to Housing Act, a broad housing bill that Congress passed in June 2026 and that took effect on July 11, 2026. The section is aimed at what the law calls a “large institutional investor,” which is a for-profit company with control over at least 350 single-family homes. Starting January 7, 2027, those companies can’t buy or otherwise acquire more one- or two-unit homes, subject to the exceptions below. Manufactured homes aren’t covered.
The limit looks forward, not backward. Large investors don’t have to sell the homes they already own. The limit is set to run for 15 years, so it would expire in January 2042 unless Congress changes it.
The law also has teeth. According to the Congressional Research Service, the Treasury Department, or the Attorney General at Treasury’s request, can go to court and seek a penalty of up to $1 million or three times the price of the home, whichever is greater. Large investors also have to report the homes they own to HUD each year.
What Treasury proposed in October
The Treasury Department published proposed rules on October 22, 2026, to spell out how the limit will work in practice. The proposal defines who counts as being “in the business of” owning and renting homes. It sets standards for homes built to rent, a safe harbor for homes bought to renovate and rent, and rules for programs that help renters become owners. It also explains when someone counts as a passive investor instead of a company in control of the homes.
These rules are a proposal, not the final word. The public gets 30 days after the proposal is published in the Federal Register to comment, and Treasury can change the details before it finalizes them. Anything I describe from the proposal could still shift.
The exceptions are bigger than the headlines
The exceptions are where most of the nuance lives. A large investor can still buy homes it builds, renovates or converts in order to sell. It can still buy newly built homes for build-to-rent communities and homes that need major rehab before they’re rented. Purchases tied to certain rent-to-own and homeownership programs are allowed, and so are homes taken back through foreclosure or to settle a debt.
There are a few more. Large investors can buy homes from other large investors that already owned them when the law passed. Homes in communities for households with someone 55 or older are excepted. There’s also a two-year transition window: through January 7, 2029, large investors can still buy from investors who aren’t covered by the law. Exactly who counts as an investor for that window is one of the details the rules are meant to settle, so I wouldn’t assume anything about a specific sale.
How many homes are we talking about?
The answer depends on where you live. The U.S. Government Accountability Office says institutional investors own about 3% of single-family homes nationally. In a March 2026 study of six metro areas, GAO found these investors owned between 1% and 3% of all single-family homes, but a much bigger share of single-family rentals, from 4% in Seattle to 22% in Jacksonville.
GAO also names Atlanta as one of the Sunbelt markets where investors have a heavier presence than the national average. Atlanta wasn’t one of the six areas in that study, so I’m not going to put a number on it. The point is that this law may be felt more in some Atlanta neighborhoods than it would be in a typical American town.
What it could mean for you
If you’re buying, the law limits one kind of buyer you might have been competing against, especially for starter homes. Christy Bunce, president of New American Funding, told National Mortgage News that buyers who need a mortgage are often at a disadvantage against cash investors and that the limit should help entry-level buyers. Other lenders in the same article were doubtful, pointing out that large investors account for a fairly small share of home purchases. GAO’s own summary describes higher prices and lower homeownership as concerns about investor buying, not proven effects. So I can’t promise you’ll see less competition, and I’d plan as if the market will feel about the same.
If you’re selling, most of the people who buy homes were never large investors, so for most homes I wouldn’t expect a big change. If homes like yours have often sold to investors, your real estate agent can tell you how common that’s been on your street and whether it’s likely to matter.
If you own a rental or two, this law isn’t aimed at you. It only reaches companies at the 350-home level. The count can include homes controlled together with partners, so if you own rentals through a larger group and you’re anywhere near that number, it’s worth asking an attorney.
What nobody knows yet
The biggest open question is whether any of this changes prices. Nobody has published a solid estimate, and the experts quoted in the news don’t agree. There’s also a question about rentals. Jamie Woodwell of the Mortgage Bankers Association warned that limits on build-to-rent investment could reduce the amount of rental housing and raise housing costs, which is the opposite of what the law intends.
The final rules are the other unknown. Treasury’s proposal could change after the comment period, and some of the exceptions will only become clear once the final rules are written. I’d treat January 7, 2027 as the date to watch and the final rules as the details to check before making any decision around them.
Questions to think through
- ☐ Am I planning to buy, sell or keep a rental in the next two years?
- ☐ If I’m selling, have investors been regular buyers on my street? Ask your agent before you price your home.
- ☐ If I’m buying, am I ready to compete with cash offers anyway? Talk with a lender early about how strong an offer you can make.
- ☐ If I own rentals with partners, do we control anywhere near 350 homes together? If so, talk to an attorney.
- ☐ Have the final rules been published yet? Check before making a decision that depends on them.
Questions about your own plans
If you’re thinking about buying or selling in the coming year, give me a call at 770-817-1550. Everyone’s situation is different, and I’m glad to talk through what the market looks like for yours.
This page is general information about a new law and a proposed rule. It isn’t legal advice, and it doesn’t describe a MiLEND loan product.